13. October 2026
Reading Time: 3
Min.
news
E-Invoicing 2027: Latest Developments and Upcoming Changes
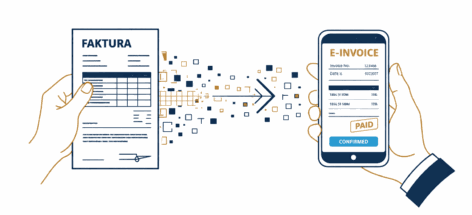
As we have already informed you in our previous articles (e-faktura-slovensko), the Slovak Financial Administration has begun implementing the e-Invoicing system, which, in its first phase, will introduce changes starting from 1 January 2027, mandatory electronic invoicing for domestic transactions.
In light of further developments in the project, we bring you an overview of the latest updates and upcoming legislative changes regarding e-Invoicing.
Technical Readiness of the e-Invoicing System
The Slovak Financial Administration has announced that the infrastructure required for the operation of the e-Invoicing system has already been established and is fully operational. Data from e-Invoices will be transmitted automatically to the Slovak Financial Administration through certified delivery service providers (so-called digital postmen).
Slovakia has thus become the first country in Europe to develop an electronic invoicing system fully aligned with the new European regulations.
Registration of Legal Entities for e-Invoicing Purposes
The Slovak Financial Administration continues to register legal entities and assign Tax Identification Numbers (TINs) ex officio to entities that have not yet been assigned one. The assignment of a TIN does not in itself give rise to a tax liability or an obligation to file a tax return.
The aim is to ensure the identification of legal entities and enable them to operate within the electronic invoicing system. The TIN serves as the primary identifier for the delivery of electronic invoices through a certified delivery service provider. Under the new system, legal entities will be required to receive e-Invoices, for example, for telecommunications services and electricity.
Certified Digital Postmen Ready for e-Invoicing
There are already 59 certified digital postmen in Slovakia, with additional delivery service providers currently undergoing the accreditation process. Several digital postmen offer an all-in-one solution that enables businesses to issue, send, receive, process and archive e-Invoices within a single platform. Simple e-Invoicing inboxes, as well as free or affordable packages, will also be available for sole traders, micro-enterprises and smaller organisations.
The Slovak Financial Administration also recommends that businesses assess the readiness of their systems before mandatory e-Invoicing is introduced and take advantage of the opportunity to participate voluntarily in the system during the transitional period.
Proposed Amendment to the VAT Act
Although mandatory electronic invoicing from 1 January 2027 has already been established by law, the ongoing implementation process is revealing several practical aspects that require amendments or clarification of the current legal framework. For this reason, the Ministry of Finance of the Slovak Republic has submitted for approval a draft amendment to Act No. Act No. 222/2004 Coll. on Value Added Tax, which proposes the following changes in the area of electronic invoicing:
- abolish the obligation for customers to report data from received e-Invoices for domestic transactions, as the same data will be reported by the supplier’s delivery service provider;
- introduce the so-called tolerance period starting from 1 January 2027 to 30 June 2027, during which the tax authorities will not impose penalties for failure to comply with the statutory 15-day deadline for issuing an e-Invoice or for failure to fulfil certain obligations related to digital reporting of data. The proposed measure aims to facilitate the transition to the new electronic invoicing regime by giving businesses time to adapt their systems, processes and technical solutions, while reducing the risk of penalties for potential initial shortcomings during the introductory phase;
- clarify the data from corrective e-Invoices that must be reported to the tax authorities. Under the proposed changes, all legally required data would have to be reported, rather than only the data that differ from the original invoice;
- introduce specific rules for corrections to invoices issued before the introduction of mandatory e-Invoicing. During the transitional period starting from 1 January 2027 to 30 June 2030, suppliers will have greater flexibility when correcting originally paper invoices, as they will be able to decide whether to issue the corrective invoice in paper or electronic form. An exception will apply to e-Invoices, where the method of issuing the corrective invoice will depend on how the original invoice was issued and delivered;
- abolish the obligation to receive e-Invoices through a delivery service for taxable persons who are not VAT payers, if the invoices received relate exclusively to the rental of immovable property exempt from VAT and the property is not included in business assets. The above will not apply if the person is required to receive e-Invoices in connection with other transactions carried out by them.